Thursday, May 6, 2010

Someone tripped over the power cord

What an unreal unraveling of the market today!  The SPY was dropping off a cliff, caused by PG company stock puking its guts out, from a hedge fund short circuit, dogs and cats- living together, mass hysteria!  I was shaking my head the rest of the day.  Just wow.

Here's what CNBC are calling the culprit:

According to multiple sources, a trader entered a "b" for billion instead of an "m" for million in a trade possibly involving Procter & Gamble 
It goes on to say "the erroneous trade may have been made at Citigroup"...I wonder how much losses resulted in this mistake?  A sell market order for over a billion shares?  It made over a 20 point move during the sell off...I would hate to be that guy.


I wonder if that is an accurate tick, that almost is too hard to believe if it is.

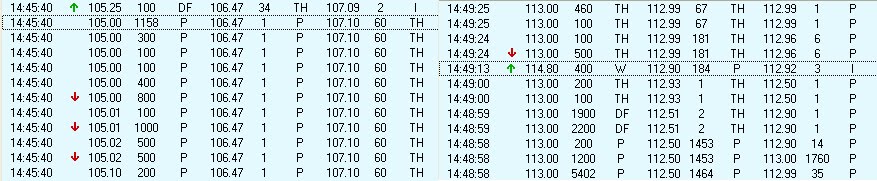
The SPY was ripped open as well, the big elevator shaft in the middle of the chart, followed with an incredible price swing from off the bottom.  The resulting move took the SPY back 9.3 points (in 3 minutes 33 seconds!)


Time and sales of the tops and bottoms


Just unreal  
As far as my savings go - I will have a pretty good May (even with having the decent expenditure to get some car repairs for state inspections) which is great since I will be able to execute on my plan to consolidate my debt into my 401k faster.  Now to stay on track I next need to set up a budget...more to follow with that.

Sunday, April 25, 2010

Fine tuning

I think my initial proposal was a good one, and it lays some pretty good groundwork for getting my debt paid down smoothly and quickly.  I was thinking about the most economical way of paying down my debt would need a bit more fine tweaking.

My largest concern is the high interest rate on my credit card, I will need to verify the % APR, but my card was one of the thousands that the credit card company sent out a letter saying they were about to raise rates, and I could cancel the card altogether if I didn't agree to the terms.  No one to blame here but myself for the account balance, but I felt a bit dirty when that happened, and now I am paying somewhere in the ballpark of 20%.

Now I don't have a bond calculator to make this into an exact calculation of interest paid, but a $7,500 account balance at that rate is about $125 per month in interest alone.  That's actually more than my car insurance and my cell phone bill together.

What I will do to change my strategy is to pay off my small 401k loan first, which could be done in about 2 months at the rate of savings I am shooting for.  Then I would look to take out a bridge 401k loan (I can have a max of 2 out at a time) to pay off my credit card completely.  This way I would no longer carry a credit card balance in about 2 months time, I would then be set to handle my accounting by funneling all expenses through the credit card asap, and lastly save myself some cash in interest.  However the downside is I would significantly reduce my 401k balance for the time being. While I do not see much upside to the market in the next few months and if it does drop, I can average back in at a lower price in my 401k...but a big missed opportunity if the market does continue to climb.

This move should save me a few hundred dollars in credit card interest, and also convert all the debt into very low interest loans, setting me up for an easier payoff time.

Tuesday, April 20, 2010

Plan of attack

My official start date for tracking my progress will be on May 1st.  For personal financial reasons, I have 1 more paycheck essentially going out the door this week, then I will be able to start taking real bites out of my liabilities.  I'm looking forward to that!   In the meanwhile I am challenged to put a plan of attack into place, and be able to hold myself accountable to that plan.  First things first, lets take a look the numbers we are up against (in order of priority):

Liabilities: $43,100
  1. Credit card:  $7500
  2. 401k Loan A:  $1960
  3. 401k Loan B:  $6330
  4. Student Loans:  $27,300
I want to start my focus on the worst of the three, the high interest card...while I can't justify a lot of balance on the credit card, I definitely remember a ski trip to Colorado that accounts for about $1500 of that which I certainly have no regrets for, that trip was unreal!    Other than that, no good excuse really - it just happened, and I need to make sure to be on top of it this time.

The 401k loans took second priority because its interest I am paying back to myself.  I wanted to put the smaller balance ahead of the larger loan to get the sense I am knocking the debt out sooner, another check mark to track.  I figured due to the size of the student loans (lengthening the payoff time), and that there is always the off chance of a default (I don't plan on a possibility of losing my job, but no one does) .  I would also like to get more back into my retirement account anyways.  It would be like a reward to get to this level, getting to contribute more.

Lastly I want to take care of my largest burden, my student loans.  The tax advantages for the interest and its sheer size make me place this third.  This list however also makes up a pretty good debt snowball approach to paying off this debt.  The idea being to start with your smallest balance loan, pay that back with as much as your budget will allow, then apply that payment to the next loan.  After a while you can make payments of much larger chunks of the account rather than the minimums.

I made a quick chart to show what my debt "curve" would look like if, on top of minimums, I committed an additional 500$:


Based on that quick analysis, it would take me 36 months to become debt free...damn that seems like a long time.  The one big difference is that I am in a position to pay this debt down, in a big way.  My living expenses are minimal for now, and I can redirect what those funds would have been into my debt.  I want to be done and done with this much faster than that.  For the time being, I am going to commit myself to try and make it 1k each month over my minimums - that would blow this out of the water in 1.5 years.  I task myself to the 1k, however I still want to contribute more if possible, anything I can really.

As part of my strategy to paying my credit card down, I have now deferred all transactions onto my credit card...everything, from bills to everyday expenses.  I know this will initially make my card balance fluctuate, and add all new velocity to the money, but this will allow me to retain the rewards points that my credit card offers (I'll take a $25 gift card to amazon for 2 months of normal every day costs, its like a reward for paying your bills for a few months).  Ultimately when the credit card balance is down to 0, I would like to continue to manage my expenses in entirely the same way, of course no longer carrying a balance.  However that is still a long ways away!

I will be fighting an uphill battle for quite some time, but the end of the race has been drawn, and now I am at starting gate.  

Here's to the challenge, an additional $1,000.00 per month towards debt.